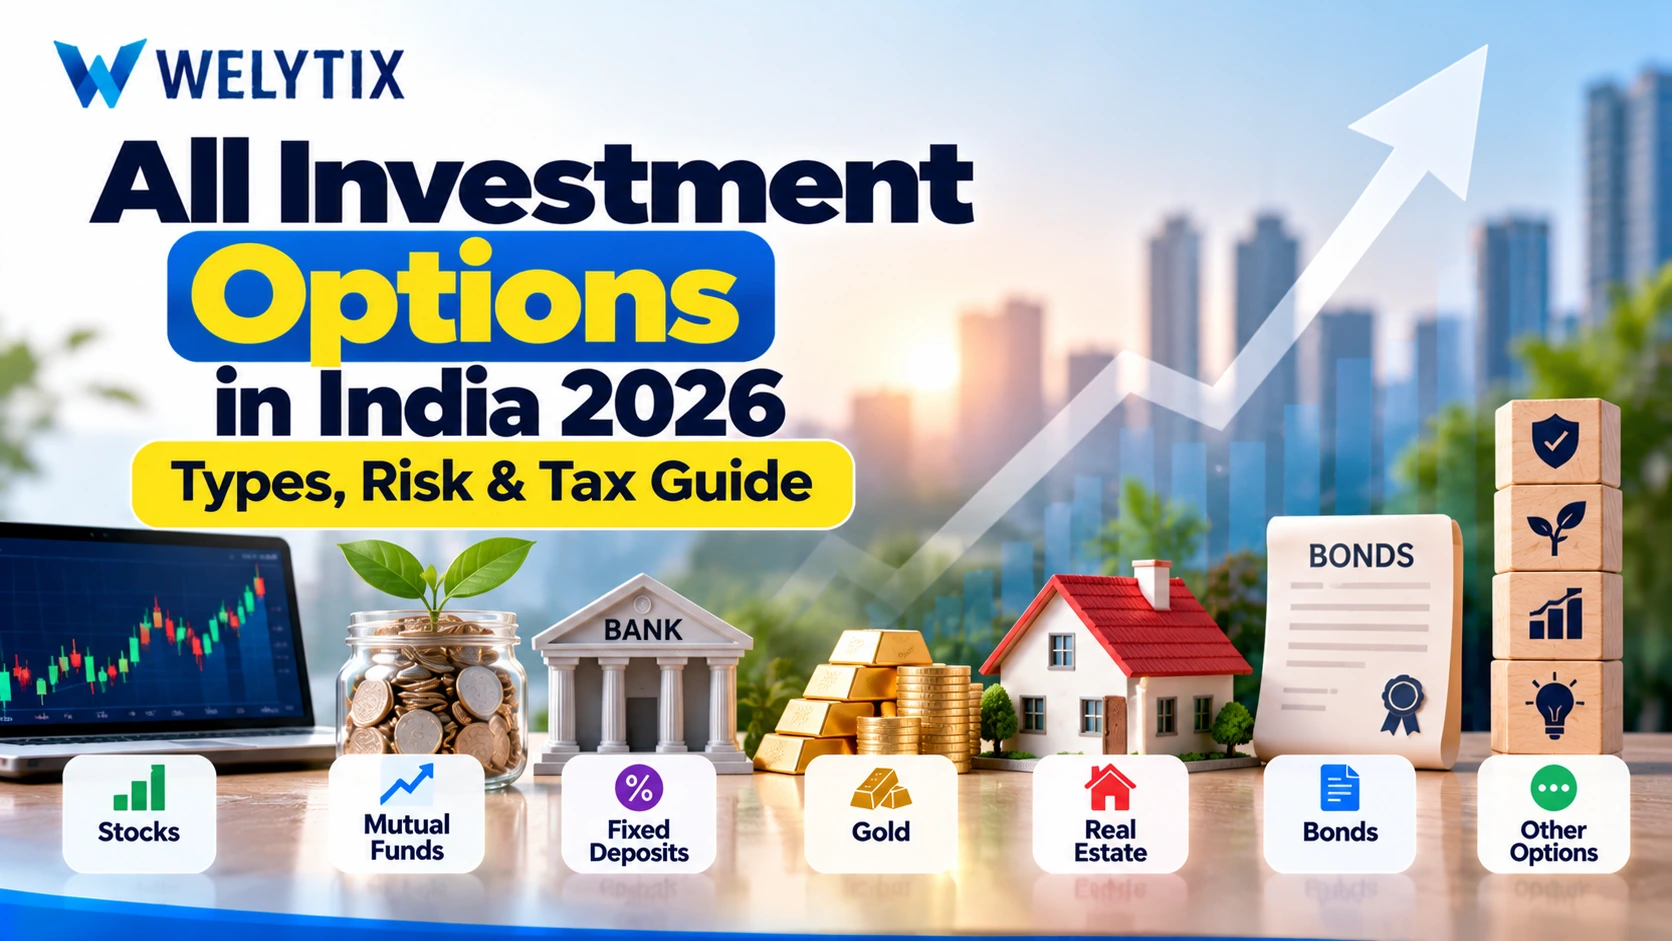
The main investment options in India are mutual funds (SIP and lumpsum), fixed deposits (FD), recurring deposits (RD), PPF, NPS, EPF, Sukanya Samriddhi Yojana, Senior Citizen Savings Scheme, post office schemes, gold, shares, REITs and bonds. There is no single best option. The right choice depends on your goal, how long you can stay invested and how much risk you can take.
This guide explains every option in simple words: who it suits, how risky it is, the lock-in period and the tax rule. Last updated: October 2026. Rates and tax rules change, so always check the official website before you invest.
Which investment option should I choose? (Quick answer)
| Your goal | Time period | Options to look at |
|---|---|---|
| Emergency fund | Any time | Savings account, liquid mutual fund, short FD |
| Trip, bike, school fees | Under 3 years | FD, RD, short-term debt funds |
| Car, house down payment | 3 to 7 years | Hybrid funds, debt funds, FD |
| Retirement, child's college | 7 years or more | Equity SIP, PPF, NPS |
| Save income tax (old regime) | 3 to 15 years | ELSS, PPF, NPS, Sukanya Samriddhi |
| Regular income after retirement | Long term | SCSS, post office MIS, SWP, FD |
What are the types of investment options in India?
Investments in India fall into three groups based on risk. Higher return usually comes with higher risk.
- Low risk (return is fixed or almost fixed): FD, RD, PPF, EPF, Sukanya Samriddhi, SCSS, post office schemes, NSC.
- Medium risk: Debt mutual funds, hybrid funds, NPS, gold, REITs, corporate bonds.
- High risk (can give higher return, but value goes up and down): Equity mutual funds, direct shares, real estate.
1. What are mutual funds and how does SIP work?
A mutual fund collects money from many investors and invests it in shares, bonds or both. A professional fund manager looks after the money. Mutual funds in India are regulated by SEBI.
You can invest in two ways:
- SIP (Systematic Investment Plan): You invest a fixed amount every month, for example ₹5,000. Many funds allow you to start with ₹100 to ₹500. SIP builds a saving habit and reduces the effect of market ups and downs.
- Lumpsum: You invest a big amount in one go. It suits you when you have extra money and a long time period.
The main types are equity funds (mostly shares), debt funds (mostly bonds), hybrid funds (a mix of both) and ELSS (tax-saving equity funds).
At a glance
- Risk: Medium to high. Returns are not guaranteed.
- Lock-in: None for most funds. ELSS has a 3-year lock-in.
- Tax: Equity fund gains on units held for more than 12 months are taxed at 12.5% above ₹1.25 lakh in a year. Gains on units held for less time are taxed at 20%. Debt fund gains are generally taxed as per your income tax slab.
- Best for: Long-term goals like retirement, child's education and wealth building.
Plan your investment with the Welytix SIP calculator, lumpsum calculator and SWP calculator.
2. What is a fixed deposit (FD)?
A fixed deposit means you keep a lump sum with a bank or NBFC for a fixed time and earn a fixed interest rate. It is simple, and you know the return in advance.
At a glance
- Risk: Low. Bank deposits are insured by DICGC up to ₹5 lakh per depositor per bank (principal and interest together).
- Lock-in: You choose the tenure, from 7 days to 10 years. Early withdrawal usually has a penalty. Tax-saving FD has a 5-year lock-in.
- Tax: Interest is added to your income and taxed as per your slab. The bank may cut TDS if interest crosses the yearly limit.
- Best for: Short-term goals and people who do not want market risk.
Use the Welytix FD calculator to see your maturity amount and interest earned.
3. What is a recurring deposit (RD)?
An RD lets you deposit a fixed amount every month for a fixed period and earn interest, like an FD. Think of it as a SIP with guaranteed return.
At a glance
- Risk: Low.
- Lock-in: Fixed tenure, usually 6 months to 10 years.
- Tax: Interest is taxable as per your slab.
- Best for: Building a saving habit without market risk.
Use the Welytix RD calculator to check how much you will get at maturity.
4. What is PPF (Public Provident Fund)?
PPF is a government-backed savings scheme for safe, long-term saving. You can open a PPF account in a bank or a post office.
At a glance
- Risk: Very low, because the government backs it.
- Lock-in: 15 years. You can extend it in blocks of 5 years.
- Limit: Minimum ₹500 and maximum ₹1.5 lakh in a financial year.
- Interest: Set by the government and reviewed every quarter.
- Tax: It is an EEE scheme. Your deposit (old regime), the interest and the maturity amount are all tax-free.
- Best for: Risk-free retirement saving and tax saving.
5. What is NPS (National Pension System)?
NPS is a pension scheme regulated by PFRDA. Your money is invested in shares, corporate bonds and government securities. At retirement, you get a lump sum, and a part of the money must be used to buy an annuity (monthly pension).
At a glance
- Risk: Medium. Returns depend on the market.
- Lock-in: Till retirement age (60), with limited early withdrawal.
- Tax: Extra deduction of up to ₹50,000 under Section 80CCD(1B) in the old tax regime, over and above the ₹1.5 lakh limit of Section 80C.
- Best for: Retirement planning at a low cost.
6. What is EPF (Employees' Provident Fund)?
EPF is a retirement saving scheme for salaried people. You and your employer both contribute 12% of your basic salary. A part of the employer share goes to the pension scheme (EPS). The government announces the interest rate every year.
At a glance
- Risk: Very low.
- Lock-in: Till retirement, with withdrawal allowed in some cases like job loss, medical need or home purchase.
- Tax: Interest is tax-free up to a yearly contribution limit. Interest above that limit is taxable.
- Best for: Salaried people who want a safe retirement fund.
You can add extra money through VPF (Voluntary Provident Fund) if you want to save more.
7. What is Sukanya Samriddhi Yojana (SSY)?
Sukanya Samriddhi Yojana is a government savings scheme for a girl child. It usually gives a higher interest rate than most other small savings schemes.
At a glance
- Who can open: For a girl child below 10 years of age.
- Deposit: Minimum ₹250 and maximum ₹1.5 lakh in a year.
- Time period: Deposits for 15 years. The account matures 21 years after opening.
- Withdrawal: Part withdrawal is allowed after the girl turns 18, for education or marriage.
- Tax: EEE benefit, same as PPF (old regime for the deposit).
- Best for: Parents who are planning for a daughter's education or marriage.
8. What is the Senior Citizen Savings Scheme (SCSS)?
SCSS is made for people aged 60 and above. It pays interest every quarter, so it works like a regular income for retired people.
At a glance
- Risk: Very low, because it is government-backed.
- Tenure: 5 years, which can be extended by 3 years.
- Limit: Up to ₹30 lakh per person.
- Tax: Interest is taxable. The deposit gets a deduction under Section 80C in the old regime.
- Best for: Retired people who need safe and regular income.
9. What are post office savings schemes?
India Post offers many small savings schemes. All of them are backed by the Government of India, so the risk is very low. Interest rates are revised every quarter, so check the India Post website for the latest rate.
- Post Office Monthly Income Scheme (MIS): Gives monthly income for 5 years.
- Post Office Time Deposit (TD): Works like a bank FD, for 1 to 5 years.
- National Savings Certificate (NSC): 5-year scheme. Qualifies for Section 80C deduction in the old regime.
- Kisan Vikas Patra (KVP): A fixed-rate certificate where your money grows over a fixed period.
- Post Office RD: A 5-year recurring deposit.
10. Is gold a good investment in India?
Gold is a popular way to protect your money from inflation and market falls. You can invest in gold in these ways:
- Physical gold: Coins, bars and jewellery. You pay making charges and need to store it safely.
- Gold ETF or gold mutual fund: You buy gold in demat form. No storage worry and no making charges.
- Sovereign Gold Bonds (SGB): These paid 2.5% yearly interest on top of the gold price gain. The government has stopped fresh issues for now, but existing bonds can be bought and sold on the stock exchange.
Many planners suggest keeping gold at around 5% to 10% of your total investments. Gold price can fall in the short term, so it is not risk free.
11. Should I invest in shares (direct stocks)?
When you buy shares, you become a part owner of a company. Shares can give high returns over a long time, but prices can fall sharply in the short term. You need a demat account and a trading account, and you must study the company before you buy.
- Risk: High.
- Lock-in: None.
- Tax: Same as equity funds. Gains on shares held for more than 12 months are taxed at 12.5% above ₹1.25 lakh in a year, and gains on shares held for less time are taxed at 20%.
- Best for: Experienced investors who can handle ups and downs and do not need the money for 5 years or more.
12. What are real estate and REITs?
Buying a house or plot can give rent and price growth over time. But it needs a big amount, has high costs like stamp duty and brokerage, and is hard to sell quickly.
If you want real estate without buying a property, you can invest in a REIT (Real Estate Investment Trust). A REIT owns offices and malls, and shares the rent income with investors. REITs are regulated by SEBI and trade on the stock exchange, so you can start with a small amount.
13. What are bonds and debentures?
When you buy a bond, you lend money to a company or the government. In return, you get regular interest and your money back at the end.
- Government securities (G-Secs): Very safe. Retail investors can buy them on the RBI Retail Direct platform.
- Corporate bonds: Pay higher interest, but carry the risk that the company may not pay. Always check the credit rating.
- Tax-free bonds: Interest is tax-free, but they are available mainly on the stock exchange.
Investment options in India: comparison table
| Option | Risk | Lock-in | Good for |
|---|---|---|---|
| Equity mutual fund (SIP) | High | None (ELSS: 3 years) | 5+ years |
| Debt mutual fund | Low to medium | None | 1 to 5 years |
| Fixed deposit | Low | Fixed tenure | 1 to 5 years |
| Recurring deposit | Low | Fixed tenure | 1 to 5 years |
| PPF | Very low | 15 years | 15+ years |
| NPS | Medium | Till age 60 | Retirement |
| EPF | Very low | Till retirement | Retirement |
| Sukanya Samriddhi | Very low | 21 years | Girl child goals |
| SCSS | Very low | 5 years | Regular income after 60 |
| Gold | Medium | None | 5+ years |
| Direct shares | High | None | 5+ years |
| REIT | Medium | None | 5+ years |
How do I start investing in India?
- Complete KYC. Keep your PAN, Aadhaar and bank account ready.
- Write down your goal and time period. For example, ₹10 lakh for a child's college in 12 years.
- Keep an emergency fund. Save 6 months of expenses in a savings account, liquid fund or short FD.
- Take insurance first. Buy a health insurance and a term insurance plan before you invest.
- Choose your products. Match each goal with the right option from the table above.
- Start small and be regular. A monthly SIP of even ₹500 is a good start.
- Review once a year. Increase your SIP when your income grows.
What are common investing mistakes to avoid?
- Investing without a clear goal.
- Following friends or social media tips blindly.
- Believing in schemes that promise guaranteed high returns. This is a common sign of fraud.
- Stopping your SIP when the market falls.
- Putting all your money in one option.
- Ignoring inflation, which slowly reduces the value of low-return savings.
How can I check my returns before I invest?
Numbers make decisions easier. In any calculator, change the amount, rate and time period to see how a small change can make a big difference over the years. More calculators are listed below.
Frequently asked questions
Which is the best investment option in India? There is no single best option. For long-term goals of 7 years or more, equity mutual funds through SIP, along with PPF and NPS, suit most people. For short-term goals, FD, RD and debt funds are better.
Which is the safest investment in India? Government-backed schemes like PPF, Sukanya Samriddhi, SCSS and post office schemes are considered the safest. Bank FDs are also safe up to the ₹5 lakh DICGC insurance limit.
Which investment gives the highest return in India? Over long periods, equity investments like shares and equity mutual funds have given higher returns than fixed-income options. But the returns are not guaranteed and can be negative in some years.
Which investments save tax in India? Under the old tax regime, you can claim deductions for ELSS, PPF, NPS, Sukanya Samriddhi, NSC, SCSS and tax-saving FD. These Section 80C deductions are not available in the new tax regime.
How much should I invest every month? A common thumb rule is to invest around 20% of your monthly income. If that is too high today, start with a smaller amount and increase it every year.
Can I start investing with ₹500? Yes. You can start a SIP, an RD or a PPF account with ₹500. A Sukanya Samriddhi account can be opened with just ₹250.
Is SIP better than lumpsum? SIP is better for salaried people because you invest a little every month and the market timing risk is lower. Lumpsum can work when you have a big amount and a long time period.
Are mutual fund returns guaranteed? No. Mutual fund returns depend on the market, and they can be higher or lower than expected.
Where can I check official information?
Always confirm rates and rules on the official websites: SEBI (sebi.gov.in) for mutual funds and shares, RBI (rbi.org.in) for banks and government securities, PFRDA (pfrda.org.in) for NPS, EPFO (epfindia.gov.in) for EPF, India Post (indiapost.gov.in) for post office schemes, and the Income Tax Department (incometax.gov.in) for tax rules.
Disclaimer: This article is for education only and is not investment, tax or legal advice. Mutual fund investments are subject to market risks. Read all scheme-related documents carefully. Interest rates and tax rules change from time to time, so please check the latest details and speak to a SEBI-registered investment adviser before you invest.