Growing your money starts with knowing where to put it. Whether you are making your first investment or fine-tuning an existing portfolio, it helps to understand what each option offers, what it risks, and who it suits best. This guide walks you through the most popular investment options in plain language, with simple rupee examples.
Quick Overview
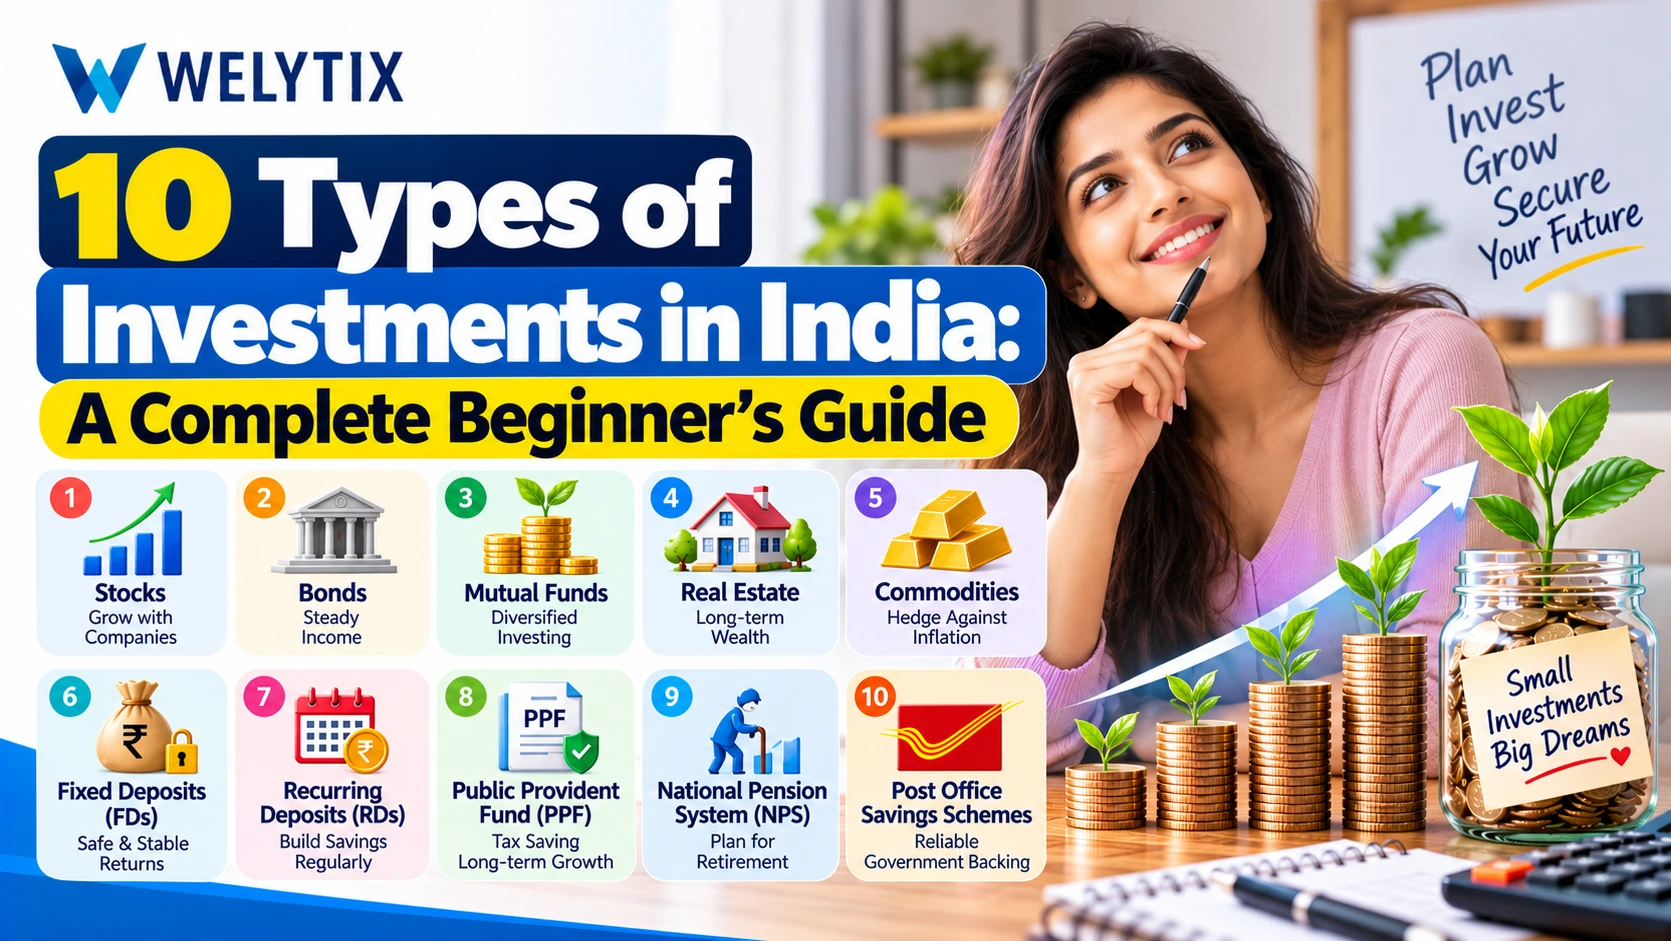
The options covered here are stocks, bonds, mutual funds, real estate, commodities, fixed deposits (FDs), recurring deposits (RDs), the Public Provident Fund (PPF), the National Pension System (NPS) and Post Office savings schemes. Each carries a different mix of risk, return and liquidity, so the right choice depends on your goals, your time horizon and how much ups and downs you can tolerate.
1. Stocks
Buying a stock means owning a small part of a company. If the business grows and does well, your shares can rise in value. If it struggles, they can fall.
Example: You buy 10 shares at ₹1,000 each, investing ₹10,000. If the price rises to ₹1,500, your shares are worth ₹15,000 and you gain ₹5,000. If it drops to ₹500, your holding falls to ₹5,000 and you face a loss of ₹5,000.
Stock prices can move sharply, sometimes within a single day. That is why spreading your money across different companies and sectors is so important. Stocks generally suit investors with a long horizon and a higher risk appetite.
2. Bonds
A bond is essentially a loan you give to a government or a company. In return, the issuer pays you regular interest and returns your original amount when the bond matures. Bonds are generally considered less risky than stocks and offer more predictable income, although they are not risk-free, since the issuer can default or interest rates can change.
Example: You buy a government bond worth ₹10,000 at 5% interest per year. You receive ₹500 every year, and at the end of the term (say, 10 years) you get your ₹10,000 back.
Bonds work well for steady income and for balancing the risk of a stock-heavy portfolio.
3. Mutual Funds
A mutual fund pools money from many investors and invests it in a mix of stocks, bonds or other assets. A professional fund manager makes the buying and selling decisions, so you get diversification without picking each security yourself.
Example: Say you have ₹50,000 to invest but are unsure which stocks to choose. A diversified equity fund can spread that amount across sectors such as technology, healthcare and energy. If one sector has a bad year, the others can help cushion the impact.
Mutual funds can be started with small amounts, including monthly SIPs, which makes them popular with beginners. Returns are market-linked and not guaranteed, so choose a fund that matches your goal and time horizon.
4. Real Estate
Real estate means buying land, a home or commercial property in the hope that its value will rise over time. It can also earn you rental income along the way. However, it needs a larger amount of money, and property cannot be sold as quickly as stocks or mutual fund units.
Example: You buy a property for ₹50 lakh in a developing area. Years later, you sell it for ₹70 lakh, a gain of ₹20 lakh, and you may also have earned monthly rent in the meantime.
Keep in mind costs like registration, maintenance and taxes when judging your actual returns.
5. Commodities
Commodities include gold, silver, crude oil and agricultural products. They can be bought physically (like gold coins or jewellery) or through gold funds, ETFs and other commodity-linked products. Many investors use them as a hedge against inflation, and gold in particular often gains attention during uncertain economic times.
Example: You invest ₹5 lakh in gold. If gold prices rise because of inflation or global uncertainty, the value of your investment rises too.
Commodity prices can swing widely with global demand and supply, so they are best used as a smaller part of a diversified portfolio. Tax treatment depends on how you hold them and for how long, so check the current rules.
6. Fixed Deposits (FDs)
An FD lets you deposit a lump sum with a bank for a fixed period, from a few months to several years, and earn a fixed rate of interest. FD rates are usually higher than savings account rates but lower than the potential returns from market-linked options.
Example: You deposit ₹1 lakh in an FD for 3 years at 6% per annum. With simple interest, you earn ₹18,000 and receive ₹1.18 lakh at maturity. (FD rates vary by bank and tenure, and if the bank compounds interest, the final amount will be slightly higher. The 6% rate here is only an assumption.)
FDs suit conservative investors who value safety and certainty, and those saving for short-term goals.
7. Recurring Deposits (RDs)
An RD works like an FD, but instead of one lump sum you deposit a fixed amount every month. At the end of the term, you receive your total deposits plus the interest earned. It is a simple way to build a savings habit.
Example: You deposit ₹5,000 every month for 3 years at an assumed 7% interest (actual RD rates vary by bank and post office). Your total contribution is ₹1.8 lakh, and at maturity you receive roughly ₹1.99 lakh, depending on the bank’s compounding method.
RDs are ideal if you cannot invest a large amount at once but can commit to a regular monthly amount.
8. Public Provident Fund (PPF)
PPF is a government-backed long-term savings scheme. You can invest between ₹500 and ₹1.5 lakh a year, and your money stays locked in for 15 years, with limited partial withdrawals allowed after a few years. The interest rate is set by the government and reviewed every quarter; it is 7.1% per annum for October–December 2026. Under the old tax regime, deposits qualify for a deduction under Section 80C, and the interest and maturity amount are tax-free. The new tax regime does not offer the 80C deduction.
Example: You invest ₹10,000 every month (₹1.2 lakh a year) for 15 years, so your total contribution is ₹18 lakh. At the current rate of 7.1% (which may change), the maturity amount would be roughly ₹31.5 lakh. This is an estimate for illustration only.
PPF suits investors who want safe, tax-efficient, long-term growth and are comfortable with a long lock-in.
9. National Pension System (NPS)
NPS is a retirement-focused scheme regulated by the government. Your contributions are invested in a mix of equity, corporate bonds and government securities, and you can choose how much goes into each within the allowed limits. You can generally withdraw only after retirement age. At exit, part of the corpus must be used to buy an annuity that pays a regular pension. Under the exit rules revised by PFRDA in December 2025, non-government subscribers can take a larger share as a lump sum than before, and small corpuses can be withdrawn in full, so check the latest exit rules on the official NPS Trust or PFRDA website.
Example: You invest ₹5,000 every month for 25 years, contributing ₹15 lakh in total. If your investments grow at an assumed 10% a year (not guaranteed, for illustration only), the corpus could be around ₹66 lakh.
On tax, an extra deduction of up to ₹50,000 under Section 80CCD(1B) is available under the old tax regime only, while an employer’s contribution to your NPS account remains deductible under Section 80CCD(2) in both regimes. Annuity income is taxable as per your slab. It works best for people who want to build a disciplined retirement fund early.
10. Post Office Savings Schemes
India Post offers several small savings schemes backed by the government, including the National Savings Certificate (NSC), the Senior Citizens Savings Scheme (SCSS), the Monthly Income Scheme and Sukanya Samriddhi Yojana. Interest rates are set by the government and reviewed every quarter, and each scheme has its own tenure, limits and eligibility. For October–December 2026, the rates are unchanged: NSC 7.7%, Senior Citizens Savings Scheme 8.2%, Monthly Income Scheme 7.4% and Sukanya Samriddhi Yojana 8.2%.
Example: You invest ₹50,000 in an NSC for 5 years at the current rate of 7.7%, compounded yearly. At maturity, you receive roughly ₹72,450. The NSC rate is fixed at the time you invest.
These schemes are popular with conservative investors, retirees and parents saving for a daughter’s future, since the returns are predictable and the risk is low.
Quick Comparison
| Investment | Risk | Liquidity | Best for |
|---|---|---|---|
| Stocks | High | High | Long-term growth |
| Bonds | Low to medium | Medium | Steady income |
| Mutual funds | Low to high, by fund type | High | Diversified, goal-based investing |
| Real estate | Medium | Low | Appreciation and rental income |
| Commodities | Medium to high | Medium | Inflation hedge |
| Fixed deposits | Low | Medium | Safe, short-term goals |
| Recurring deposits | Low | Medium | Building a savings habit |
| PPF | Very low | Low | Long-term, tax-efficient savings |
| NPS | Low to medium | Low | Retirement planning |
| Post office schemes | Very low | Low to medium | Conservative, predictable returns |
How to Choose the Right Investment
There is no single best option. A few simple questions can guide you:
- What is your goal? Wealth creation, regular income, or short-term savings?
- What is your time horizon? Longer horizons can usually handle more market risk.
- How much risk can you take? Be honest about how you would feel if your investment fell in value.
- Do you need quick access to your money? Stocks and mutual funds are generally easier to sell than property.
Most investors do best by combining a few of these options rather than relying on just one.
Conclusion
Stocks, bonds, mutual funds, real estate, commodities, FDs, RDs, PPF, NPS and Post Office schemes each play a different role. Some aim for growth, some for stability, and some for regular income. The key is to understand the risks, diversify wisely, and match your choices to your financial goals. Start small, stay consistent, and review your portfolio from time to time.
Disclaimer: This blog is for educational and informational purposes only and does not constitute investment, tax or legal advice. Interest rates, tax rules and scheme terms mentioned are as of October 2026 and may change. Examples use assumed returns for illustration and do not guarantee future results. Investments in securities markets are subject to market risks. Please read all related documents carefully and consult a qualified financial advisor or tax professional before investing.