SIP or FD? It’s one of the most common money questions in India, and the honest answer is: it depends on your goal, your timeline and how much risk you can handle. Let’s compare them side by side, with real numbers.
SIP vs FD: the quick answer
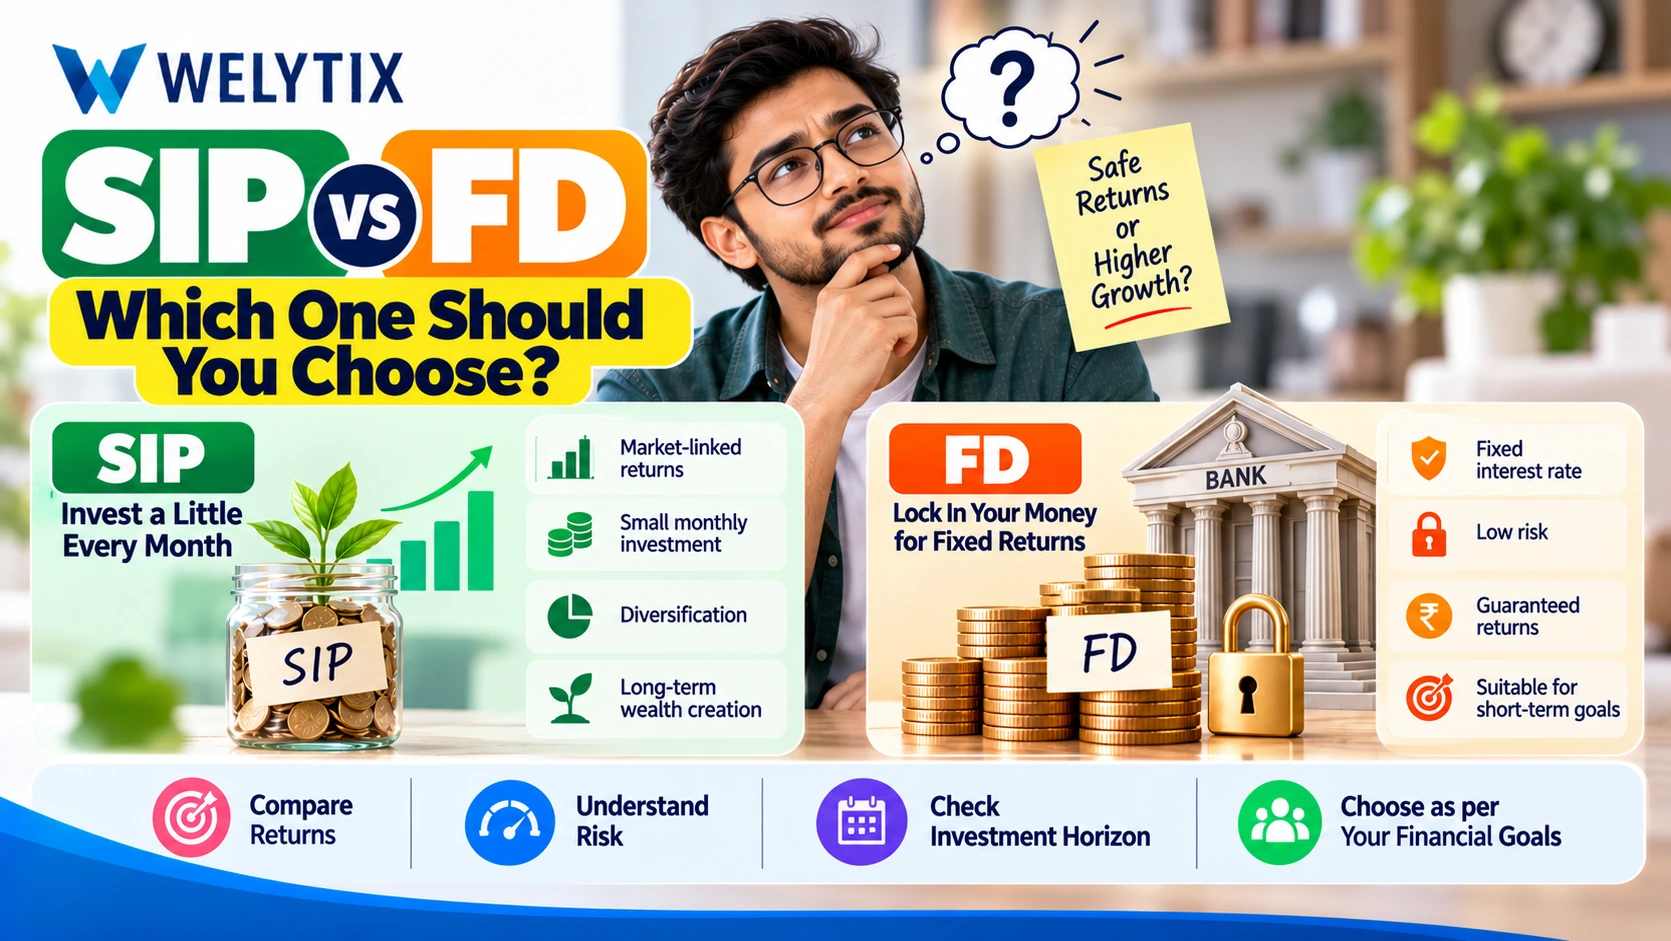
An FD gives guaranteed returns and is best for safety and short-term goals. A SIP invests in mutual funds, carries market risk, and is better suited for long-term goals of 5 years or more.
Neither one is better for everyone. Many people use both: FD for money they can’t afford to risk, SIP for money they won’t need for years.
SIP and FD in simple words
What is a SIP?
A SIP (Systematic Investment Plan) lets you invest a fixed amount in a mutual fund every month. Your returns depend on how the market performs, so they are not guaranteed. You can estimate them with the SIP Calculator.
What is an FD?
An FD (Fixed Deposit) is a lump sum you deposit with a bank or NBFC for a fixed period at a fixed interest rate. You know your maturity amount on day one. You can check it with the FD Calculator.
SIP vs FD: side-by-side comparison
| Point | SIP | FD |
|---|---|---|
| How you invest | Fixed amount every month | One lump sum |
| Returns | Market-linked, not guaranteed | Fixed, known upfront |
| Risk | Higher (value can go up and down) | Very low |
| Best time horizon | 5 years or more | 7 days to 10 years |
| Starting amount | As low as ₹500 a month on many schemes | Depends on the bank |
| Liquidity | Can redeem anytime (exit load may apply) | Premature withdrawal usually carries a penalty |
| Tax on gains | Equity funds: 20% (12 months or less), 12.5% above ₹1.25 lakh (longer) | Added to income, taxed as per your slab |
| Beating inflation | Has the potential to, over the long run | May struggle, especially after tax |
Let’s compare with real numbers
Same ₹5,000 every month for 10 years
You invest ₹6,00,000 in total. The fixed option below is an RD-style deposit at 7%. SIP returns are assumptions, not promises.
| Option | Approx. value after 10 years |
|---|---|
| Fixed deposit-style savings at 7% | ₹8.69 lakh |
| SIP at 5% | ₹7.80 lakh |
| SIP at 8% | ₹9.21 lakh |
| SIP at 10% | ₹10.33 lakh |
| SIP at 12% | ₹11.62 lakh |
Look at the first two rows. If the SIP earns only 5% a year, the fixed option actually wins. If the SIP earns 10% or more, it comes out well ahead. That’s the trade-off: a SIP can earn more, but it may not.
₹1 lakh in an FD at 7%
(Interest compounded quarterly)
| Tenure | Approx. maturity amount |
|---|---|
| 5 years | ₹1,41,478 |
| 10 years | ₹2,00,160 |
Your money roughly doubles in 10 years, and you know this from day one. Try your own numbers on the FD Calculator.
Tax: which one is better?
- FD: Interest is added to your income and taxed as per your slab. A person in the 30% slab keeps only around 4.8% from a 7% FD, after tax. Banks also deduct TDS once interest from one bank crosses ₹50,000 a year (₹1,00,000 for senior citizens).
- SIP (equity funds): Gains held for 12 months or less are taxed at 20%. Gains held longer are taxed at 12.5%, and the first ₹1.25 lakh of long-term gains each year is tax-free.
For long holding periods, equity funds are often taxed more lightly than FD interest. But tax rules change and depend on the type of fund, so confirm the latest details with a tax advisor.
Which one suits your goal?
| Your goal | Usually a better fit |
|---|---|
| Emergency fund | FD (safe and easy to access) |
| Goal in less than 3 years | FD |
| Goal 5 years or more away | SIP |
| Retirement planning | SIP, often along with safer options |
| Regular safe income as a senior citizen | FD |
| Starting small from your monthly salary | SIP (or an RD if you want fixed returns) |
This is a general guide, not personal advice. Your own situation may differ.
Can you invest in both?
Yes, and many people do. A simple way to think about it:
- Keep money you may need soon, like an emergency fund, in an FD.
- Put money you won’t touch for 5+ years in a SIP.
- Review the split as your income, goals and comfort with risk change.
Check how both grow over time with the Inflation Calculator, because safe returns that don’t beat inflation lose buying power quietly.
Common mistakes to avoid
- Putting long-term money only in an FD. After tax and inflation, your real returns may be very low.
- Putting short-term money in a SIP. Markets can fall just before you need the money.
- Judging a SIP by one bad year. Look at how it does over 5 to 10 years.
- Ignoring tax. Compare returns after tax, not before.
- Assuming SIP returns are guaranteed. The calculator shows an estimate, not a promise.
- Breaking an FD early. You may lose part of the interest to a penalty.
Frequently Asked Questions
Which is better, SIP or FD?
It depends on your goal. FD is better for safety and goals less than 3 years away. SIP is better for long-term goals of 5 years or more, when you can handle market ups and downs.
Is SIP safer than FD?
No. An FD is safer because your interest rate is fixed. A SIP invests in mutual funds, so its value can fall in the short term.
Which gives higher returns, SIP or FD?
SIPs have the potential to give higher returns over the long run, but they are not guaranteed. FD returns are lower but fixed.
Can I invest in both SIP and FD?
Yes. Many people keep short-term and emergency money in an FD and invest long-term money through a SIP.
Which is better for the short term?
An FD is usually better for the short term because your returns are fixed and your money isn’t exposed to market falls.
Which is better for tax?
It depends on the fund type and how long you hold. FD interest is taxed as per your slab. Equity fund gains get lower long-term rates after 12 months. Check the latest rules with a tax advisor.
Is a SIP better than an RD?
They suit different needs. A SIP is market-linked and can grow more, but it carries risk. An RD gives fixed returns with very low risk. Compare them with the RD Calculator.
Related calculators
Browse all tools on the Welytix Financial Calculators page.
Final thoughts
You don’t have to pick a side. Use an FD where safety matters most, and a SIP where time is on your side. Try the Welytix SIP Calculator and the Welytix FD Calculator with your own numbers and see which fits your goal.
Disclaimer: This content is for educational purposes only and is not financial advice. Mutual fund investments are subject to market risks. Interest rates and tax rules change, so please confirm current details with your bank, a SEBI-registered advisor or a tax professional.